

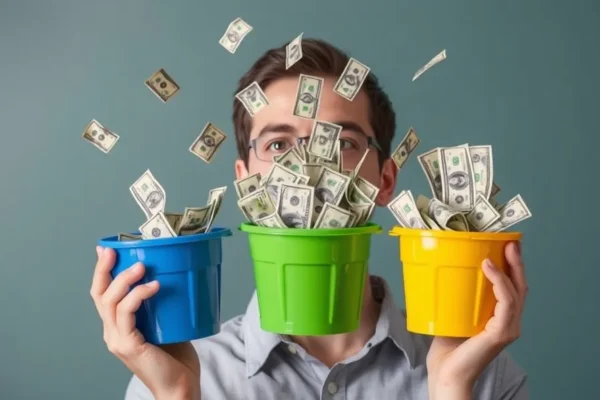
When Your Brain Puts Money in Different Pockets
Ever found yourself treating a tax refund differently than your regular paycheck? Or maybe you’re super careful with money you’ve earned yourself, but a bit more relaxed with a gift of cash? If this sounds like you, you’ve stumbled upon a fascinating quirk of human behavior that touches on how we think about money. It’s a concept called mental accounting. Basically, instead of seeing all our money as interchangeable, our brains tend to create invisible “accounts” or “mental buckets” for different sums of money. We then make different decisions about how to spend, save, or invest based on which mental bucket the money came from.
Think of it like this: your brain doesn’t have one giant vault for all your cash. Instead, it’s got little labeled boxes. One might say “Hard Earned,” another “Windfall,” and maybe another “Emergency Fund.” The money in each box gets treated with a different set of rules, even if, in reality, it’s all just money.
Why We’re Suddenly Talking About This “Money Mindset”
You might be wondering why this topic is popping up now. In a world where financial literacy is a hot topic and everyone’s looking for better ways to manage their money, understanding the psychological forces at play is key. As more people delve into behavioral finance, they’re uncovering these mental shortcuts our brains take. This leads to a deeper understanding of our own spending habits and saving strategies. It’s not just about numbers on a spreadsheet; it’s about the feelings and perceptions we attach to those numbers. This is why mental accounting is gaining traction – it offers a relatable explanation for why we sometimes make seemingly irrational financial decisions.
A Peek Behind the “Mental Budget” Curtain
The idea of mental accounting isn’t entirely new, though the term was popularized by Nobel laureate Richard Thaler. For ages, people have intuitively known that money feels different depending on its source. A bonus at work might feel like “fun money,” while money saved from daily lunches feels like a significant achievement. Behavioral finance, as a field, started to systematically study these patterns, showing us that our decision making isn’t always purely rational. It’s influenced by our emotions, our past experiences, and how we mentally categorize things.
This concept is a cornerstone of behavioral finance. It explains why we might splurge with a lottery win but be thrifty with our salary. Our brains create these separate mental accounts, influencing how we perceive value and make choices about money management. It’s a reminder that our financial psychology plays a huge role in our personal finance.
How This “Mind Over Money” Game Affects Us
The impact of mental accounting on our personal finance can be pretty significant. It shapes our spending habits and saving strategies in ways we might not even realize. When you get a bonus, your mental account for “found money” might be open for a lavish purchase. But if that same amount came from painstakingly cutting back on daily expenses, you might see it as a testament to your saving strategies and decide to add it to your investments.
Here’s a look at some common ways it plays out:
- Splurging on “Fun Money”: That tax refund or gift? It often goes into a mental bucket labeled “treat yourself.” This can lead to impulse buys that might not align with broader financial goals.
- Pain of Losing: We often feel the pain of a loss more intensely than the pleasure of an equivalent gain. Mental accounting can amplify this. If you lose $20 from your wallet, you might feel more upset than if you found $20.
- Separate Budgets: People often create different mental budgets for different categories, like “vacation fund” or “car savings.” While this can be helpful for goal setting, it can also lead to overspending in one area because you feel you have “separate” money for it.
- Underestimating Opportunity Cost: Because money is mentally compartmentalized, we might not fully consider what we’re giving up by spending from one “account” versus another. For example, spending a vacation fund on a new gadget might feel okay because it’s “vacation money,” but it means sacrificing the vacation itself.
For businesses, understanding mental accounting can be a powerful tool. They can frame offers and products in ways that tap into these mental buckets, influencing consumer spending habits. For example, offering a “buy one, get one free” deal might feel like getting extra value in a specific “deal” account, making it more appealing than a straight discount on a single item.
What’s Next for Our Financial Brains?
As awareness of mental accounting grows, we’re likely to see a greater emphasis on developing more conscious money management skills. This means actively trying to break down these mental barriers and treat all money with a consistent level of care, regardless of its source. Tools and apps that help visualize your entire financial picture, rather than just individual accounts, could become more popular. The goal isn’t to eliminate these mental shortcuts entirely, as they can sometimes be useful for motivation and goal setting. Instead, it’s about becoming more aware of them so we can make more informed and deliberate financial decisions.
The future might involve more sophisticated financial planning tools that account for these psychological biases, helping individuals align their spending and saving with their long-term goals, rather than their short-term emotional perceptions of money. It’s about bringing more unity to our financial lives.
Your Burning Questions About Mental Accounting Answered
What exactly is mental accounting in behavioral finance?
Mental accounting is a concept from behavioral finance where individuals mentally separate their money into different “accounts” or “buckets.” They then make different spending or saving decisions based on which mental account the money belongs to, rather than treating all money as fungible. This affects their personal finance and money management.
How does mental accounting influence my spending habits?
Mental accounting can lead to varied spending habits. For example, you might be more inclined to splurge with a bonus or tax refund because it’s mentally categorized as “windfall” money, while being more cautious with your regular paycheck. This is a key aspect of understanding your decision making regarding personal finance.
Can mental accounting affect my saving strategies?
Absolutely. If you mentally earmark money for specific goals like a vacation or a down payment, you might be more likely to save for those things. However, it can also lead to overspending in other areas because you feel that “dedicated” money is separate from your overall funds. This impacts your overall saving strategies and financial psychology.
Is mental accounting related to budgeting?
Yes, mental accounting is closely related to budgeting. While a formal budget is a structured plan, mental accounting refers to the subconscious way we categorize money, which then influences how we stick to or deviate from our budgets. Understanding mental accounting can improve your budgeting and money management skills.
How can I overcome the negative effects of mental accounting on my personal finance?
To overcome its negative effects, try to view all your money as part of one larger pool. Consolidate accounts where possible, and consciously ask yourself if a purchase aligns with your overall financial goals, regardless of where the money “came from.” Developing mindful decision making is key to better personal finance and effective money management.











