The simple truth about the money you earn versus the money you have
Imagine you just landed a great new job. Your offer letter says you make 60,000 dollars a year. On paper, you are doing great. You feel a sense of accomplishment because your income has increased. But then, the first month hits. You have a large security deposit for a new apartment, a car repair that you did not see coming, and a few annual subscriptions that all renew in the same week. Suddenly, even though you have a high salary, your bank account is hovering near zero.
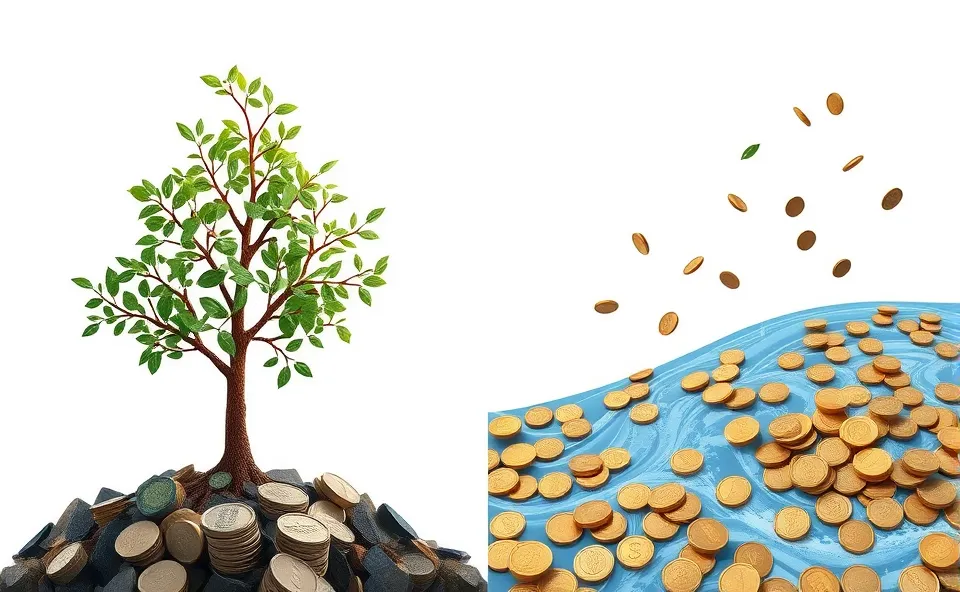
This is the exact moment where most people realize that income and cash flow are not the same thing. Income is a number on a page. It is the total amount of money you are entitled to receive. Cash flow, however, is the actual movement of money in and out of your pocket. It is about timing. It is the difference between knowing you will be paid on Friday and having the money in your hand on Tuesday to pay a bill.
When we talk about income, we are usually talking about revenue. If you are a freelancer, it is the total of all the invoices you sent this month. If you are an employee, it is your gross salary. But cash flow is the reality of your liquidity. Liquidity is just a fancy way of saying how quickly you can spend your money. If you have a million dollars in a house but zero dollars in the bank, you have high wealth but terrible cash flow.
Why everyone is suddenly obsessed with liquidity
For a long time, personal finance was all about the big number. People focused on their annual salary or their net worth. If you earned enough, you were considered successful. But the world has changed. We now live in a gig economy where many people have multiple streams of revenue. You might have a full time job, a side hustle on Etsy, and some dividends from stocks. This makes tracking your money much more complicated.
At the same time, the cost of living has become more volatile. Prices for groceries and gas swing wildly. When expenses are unpredictable, having a high income is not enough to keep you stress free. You need to know exactly when money is arriving and when it is leaving. This is why more people are searching for better ways to handle their cash flow management.
People have realized that you can be profitable on paper but still go broke. This happens when your money is tied up in things you cannot spend, or when your bills arrive faster than your paychecks. The focus has shifted from just earning more to managing the flow of what is already earned. It is no longer just about the destination, but the journey the money takes from your employer to your bank account and eventually to your bills.
The basic accounting logic behind the curtain
To really get this, it helps to look at how businesses handle their books. In the world of accounting, there are two main ways to track money. First, there is accrual accounting. This is where you record income the moment you earn it, even if the client has not paid you yet. This tells you about your profitability. It shows if your business model actually works.
Then, there is cash accounting. This only records money when it actually hits the bank account. This is the only way to measure your operating cash flow. A company can report a huge net income for the year, but if their customers are slow to pay, the company might not have enough cash to pay its own employees. They are profitable, but they lack liquidity.
Your personal life works the same way. Your net income is what is left after you subtract your taxes and basic costs from your total earnings. But your cash flow is the daily reality. If you earn a large bonus once a year, your annual income looks great. However, if you do not spread that bonus across twelve months, you might struggle with cash flow during the other eleven months of the year.
- Revenue: The total amount of money coming in before any deductions.
- Net Income: What you actually keep after expenses and taxes.
- Operating Cash Flow: The actual cash moving in and out for your daily life.
- Liquidity: How much spendable cash you have available right now.
How this distinction changes your financial life
Once you stop focusing only on income and start focusing on cash flow, your entire approach to budgeting changes. You stop asking, “How much do I make?” and start asking, “When do I have the money?” This shift reduces a huge amount of financial anxiety.
When you manage for cash flow, you start to build a buffer. You realize that a high income can actually be a trap if you increase your lifestyle to match it immediately. This is called lifestyle creep. If your income goes up but your expenses rise at the same rate, your cash flow remains tight. You are essentially running on a treadmill, earning more but never actually feeling the benefit in your bank account.
Better financial management means aligning your expenses with your income timing. Instead of paying every bill the moment it arrives, you might set up a system where payments align with your paydays. You start to value liquidity over prestige. You might choose a slightly lower paying job that pays weekly over a higher paying job that pays monthly if it helps you manage your stress and avoid high interest short term loans.
What the future of money management looks like
We are moving toward a world of real time finance. For decades, we relied on monthly bank statements. You would look at your spending at the end of the month and wonder where the money went. That is a reactive way to live. The future is all about proactive, real time cash flow tracking.
We are seeing the rise of AI tools that do more than just categorize your spending. New technology is starting to predict your cash flow. These tools can look at your historical data and warn you that your account will be low in two weeks because three different subscriptions are due at the same time. They help you bridge the gap between your income and your spending without you having to manually update a spreadsheet.
We will likely see a bigger shift toward dynamic budgeting. Instead of a static monthly budget, people will use fluid systems that adjust based on their current liquidity. The goal will not be to simply hit a savings target, but to maintain a healthy flow that allows for both stability and spontaneous spending without the fear of a bounced check.
Common questions about income and cash flow
Can I have a high income but negative cash flow?
Yes, this is very common. You might earn a high salary, but if your monthly expenses, debt payments, and taxes are higher than the amount of cash you actually receive each month, you have negative cash flow. In this case, you are likely relying on credit cards or savings to survive, despite your high income.
Which is more important for personal finance, income or cash flow?
Both matter, but they serve different purposes. Income determines your long term wealth and your ability to build assets. Cash flow determines your daily survival and your stress levels. You need enough income to grow your future, but you need positive cash flow to function today.
How does net income differ from operating cash flow?
Net income is an accounting figure that shows your total profit after all expenses are subtracted from your revenue. Operating cash flow is the actual amount of cash that moved into and out of your bank account. Net income includes non cash items, while cash flow only cares about actual money.
How can I improve my cash flow without increasing my income?
You can improve cash flow by managing the timing of your expenses. This could mean negotiating different due dates for your bills, reducing unnecessary monthly subscriptions, or building a small cash buffer to cover gaps between paychecks. It is about managing the exit of money as much as the entry.
Why is liquidity important for budgeting?
Liquidity is important because it gives you a safety net. If an emergency happens, it does not matter if you have a high income if that money is locked in a retirement account or a house. Liquidity ensures you have the cash on hand to handle surprises without taking on high interest debt.