What Exactly is Umbrella Insurance?
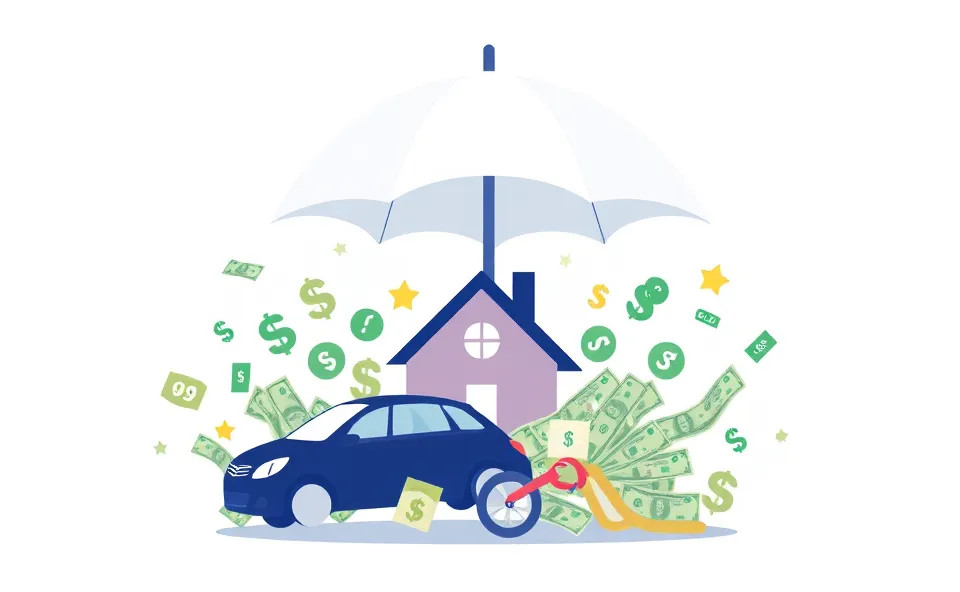
So, you’ve probably heard the term “umbrella insurance” floating around, especially if you’ve been thinking about beefing up your personal finance safety net. Let’s break it down in a way that makes sense. Think of it as an extra layer of protection, like a big, comforting umbrella, that covers you when things get really expensive. It’s not your everyday insurance for a minor fender bender or a leaky faucet. Instead, umbrella insurance steps in when the damages or legal claims against you exceed the limits of your other policies, like your homeowners or auto insurance.
Essentially, it’s a form of excess liability coverage. If someone sues you for a huge amount of money, say millions of dollars, and your standard policy limits aren’t enough to cover it, your umbrella policy kicks in to pay the rest. It offers additional coverage for those rare but potentially devastating situations. It’s like a financial superhero cape that swoops in when your regular insurance has done all it can.
Why All the Buzz About Umbrella Insurance Lately?
You might be wondering why this topic is suddenly gaining so much traction. In today’s world, we’re seeing increasingly larger lawsuits. People are more aware of their legal rights, and the potential financial fallout from an accident or incident can be astronomical. Think about a serious car accident where you’re found at fault, or a serious injury that happens to someone on your property. The medical bills and legal fees alone can skyrocket into the millions. As these risks become more apparent, people are naturally looking for robust liability protection that goes beyond what their standard policies offer. It’s a proactive move to safeguard their hard-earned assets from the unpredictable nature of legal claims.
A Little History: Building a Better Safety Net
The concept of umbrella insurance isn’t entirely new, but its prominence has grown as societal complexity and financial stakes have increased. Historically, insurance policies were more straightforward. However, as our lives became more interconnected and the potential for costly incidents grew, so did the need for more comprehensive coverage. Homeowners insurance and auto insurance have always been crucial, covering damages to your property and liability for accidents. Renters insurance also provides a level of protection for your belongings and some liability, but it too has its limits. Over time, insurers recognized that there was a gap – a need for a policy that could pick up where these standard policies left off, especially in the face of increasingly substantial liability claims. This led to the development and popularization of personal umbrella policies as a vital component of a well-rounded financial plan.
The Real Impact: Who Needs This Kind of Protection?
The impact of umbrella insurance is significant, primarily in providing crucial asset protection. So, who benefits the most from this additional coverage? It’s not just for the super-wealthy, though they certainly have a strong need. Anyone with significant assets they want to protect can benefit. This includes:
- Homeowners: If you own a home, especially in an area with higher property values, you have more to lose. A visitor could slip and fall and sue you for substantial damages.
- People with substantial savings or investments: If you’ve worked hard to build up your nest egg, an umbrella policy can shield it from being depleted by a lawsuit.
- Those with higher risk profiles: This could include people who own rental properties, own multiple vehicles, have a swimming pool, own a dog, or engage in certain recreational activities that might increase their liability.
- Individuals who are active on social media: While it might seem indirect, content shared online can sometimes lead to defamation lawsuits.
- Anyone who wants peace of mind: Knowing you have that extra layer of liability protection can alleviate a lot of stress about potential financial ruin.
In essence, if the cost to replace what you own, or the potential financial hit from a major lawsuit, would significantly impact your life, then umbrella insurance is something you should seriously consider. It’s about safeguarding your future and the future of your loved ones beyond homeowners insurance or renters insurance add-on limits.
Looking Ahead: What’s Next for This Coverage?
As the world continues to evolve, so will the risks and the insurance landscape. We can expect umbrella insurance to remain a key part of comprehensive personal finance strategies. With the rise of new technologies and changing lifestyles, potential liability scenarios may also shift. For instance, increased reliance on smart home devices or greater participation in gig economy work might introduce new considerations for liability. Insurers will likely continue to adapt their offerings to address these emerging risks, ensuring that umbrella insurance remains a relevant and essential tool for lawsuit protection and asset protection. The trend towards greater awareness of personal responsibility and the potential for significant financial consequences will likely keep the demand for this type of robust excess liability coverage strong.
Frequently Asked Questions About Umbrella Insurance
What is umbrella insurance and how does it work?
Umbrella insurance provides liability protection that goes beyond the limits of your existing homeowners, auto, or renters insurance policies. If a claim against you exceeds the coverage of your primary policies, your umbrella policy kicks in to cover the remaining damages, offering valuable asset protection.
When should I consider getting umbrella insurance?
You should consider umbrella insurance if you have significant assets you want to protect, if you have a higher risk profile, or if you simply want extra peace of mind. It’s particularly important when the potential cost of a lawsuit could exceed your current liability limits.
What is the typical umbrella insurance cost?
The umbrella insurance cost is generally quite affordable, especially considering the extensive additional coverage it offers. Premiums vary based on factors like your assets, risk factors, and the limits you choose, but it’s often a relatively small investment for significant lawsuit protection.
Does umbrella insurance cover more than just car accidents and injuries on my property?
Yes, a personal umbrella policy can cover a wide range of liability situations, including libel, slander, false arrest, and even certain situations involving your boat or other recreational vehicles, extending your liability protection significantly.
Is umbrella insurance necessary if I already have good homeowners and auto insurance?
While good homeowners insurance and auto insurance are essential, they have coverage limits. Umbrella insurance acts as an extra layer of security, offering excess liability coverage for claims that surpass those limits, providing crucial lawsuit protection and asset protection for your financial future.