

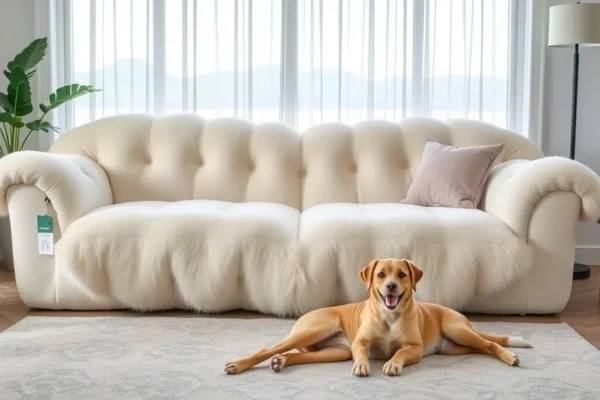
Understanding Asset Allocation and Consumer Spending
At its simplest level, financial education is about understanding the trade-off between the money you have today and the things you want tomorrow. When we discuss purchasing items like a cloud couch, we are actually discussing asset allocation. An asset is simply something of value that you own. While a piece of furniture is a depreciating asset—meaning it loses value over time—it still represents a significant portion of a household budget. Think of your money like a limited supply of fuel in a car; every dollar spent on a living room furniture upgrade is fuel you no longer have to invest in your savings or emergency fund.
Understanding this concept is vital because most people view “spending” as a separate activity from “investing.” In reality, they are two sides of the same coin. When you choose to purchase an affordable furniture item, you are making a value judgment. You are deciding that the comfort and utility of that item are worth more to you right now than the interest that same money could have earned in a high-yield savings account. Learning to weigh these decisions is the foundation of financial independence.
How Consumer Purchase Decisions Function
The mechanism behind a flash sale is designed to influence human psychology, specifically the fear of missing out, or FOMO. Imagine you have a budget of $500 for home improvements. You see a high-end, designer-style sofa listed for $2,000, which is outside your means. Suddenly, a retailer announces a deal where a similar-looking piece, a cloud couch, is available for $250. You now have a decision-making moment.
The mechanics of this purchase follow a clear path: First, the retailer identifies a market need for a comfortable couch that serves a specific demographic—in this case, pet owners. By including features like removable covers for easy cleaning, the product adds functional value. Second, the retailer uses a price reduction to lower the barrier to entry. If Person A takes the deal, they save $1,750 compared to the designer version. If they then take that $1,750 and put it into a retirement account or use it to pay down high-interest debt, they have successfully leveraged a discount to improve their overall financial position. However, if Person A uses the deal as a reason to buy items they did not actually need, they have effectively reduced their net worth by $250.
Why Smart Spending Impacts Your Financial Health
Personal financial decisions ripple outward into the broader economy. When individuals prioritize budget sofa options over luxury goods, they increase their discretionary income. This extra capital can then be channeled into the economy through investments, education, or savings, which are the building blocks of personal wealth.
From an economic perspective, consumer demand for affordable, functional items like a pet-friendly sofa drives market competition. When companies compete on price and utility, it puts downward pressure on inflation for consumer goods. The people who benefit most are those who view their spending through the lens of long-term value. Conversely, those who are negatively affected are often those who engage in impulse spending without considering the opportunity cost. Opportunity cost is the value of what you give up to get something else. If you spend your last $250 on furniture, you give up the ability to use that money for an emergency repair or a debt payment, which could lead to borrowing at high interest rates later.
The Evolution of the Affordable Furniture Market
The retail landscape has changed dramatically over the last decade. Historically, furniture was a high-ticket item expected to last a generation. However, the rise of e-commerce and global supply chain optimization has shifted the market toward “fast furniture.” As of 2024, data from the Bureau of Economic Analysis suggests that consumers are spending a higher percentage of their income on home goods compared to pre-pandemic averages, largely driven by the desire for improved living spaces during shifts in work-from-home culture.
Current interest in items like the cloud couch is triggered by a combination of social media trends and economic necessity. As inflation has impacted the cost of living, consumers are seeking ways to maintain a certain quality of life—specifically comfort and aesthetics—without overextending their budgets. This has forced retailers to focus on the “budget sofa” segment, resulting in flash sale events that target value-conscious shoppers who prioritize utility, such as pet-friendly features, over brand names.
Practical Implications for Your Financial Life
When you encounter a deal on items like a comfortable couch, you should look past the marketing. Ask yourself two questions: “Do I truly need this, or am I being prompted by the price?” and “What else could this money do for me today?”
A common misconception is that “cheap” always means “bad” or that “expensive” always means “better.” In reality, value is found in the intersection of price, durability, and function. A pet-friendly sofa with removable covers might actually save you money in the long run if it prevents you from having to replace the entire piece due to stains or damage. To manage your finances effectively, avoid viewing deals as an excuse to spend. Instead, see them as an opportunity to acquire a necessary item at a lower cost, thereby freeing up your remaining budget for higher-priority financial goals. Always research the return policy and the long-term utility of the item before finalizing a purchase.
Connecting Purchases to Broader Financial Concepts
Your choices regarding home furnishings are deeply connected to other financial pillars. Understanding the concept of depreciation is crucial here; unlike a home or a stocks portfolio, a piece of living room furniture typically loses value the moment it is removed from the box. This makes it a consumption expense rather than an investment.
Furthermore, these decisions relate to your debt-to-income ratio. If you use a credit card to finance a $250 purchase and do not pay it off within the billing cycle, you will be charged interest, turning that “deal” into a much more expensive purchase. Understanding the difference between assets and liabilities is the next step in deepening your knowledge of personal finance. For more on this, you may want to research how to build an emergency fund before making discretionary purchases.
Common Questions About Consumer Spending
How do Walmart deals impact my long-term savings?
While Walmart deals can help you save money on necessary items, they only positively impact your long-term savings if you take the money you “saved” and put it into a savings or investment account. If the discount simply encourages you to buy more than you planned, it does not contribute to your long-term financial health.
Is a pet-friendly sofa a good financial investment?
Furniture is generally not considered an investment because it does not appreciate in value. However, a pet-friendly sofa with removable covers can be a “good purchase” if it serves your needs for a long time and prevents the need for more expensive replacements or professional cleaning services.
How does inflation affect the cost of affordable furniture?
Inflation increases the costs of raw materials and shipping, which forces retailers to raise prices. This is why a flash sale on a budget sofa is a common strategy; retailers must move inventory quickly to keep their cash flow moving in an environment where consumers have less discretionary income.
What is the biggest risk when buying living room furniture?
The biggest risk is “lifestyle creep,” where you spend money you don’t have on things you don’t need simply because they are on sale. This can lead to reliance on credit, which introduces high-interest debt that can take years to pay off.
Can I use a cloud couch to improve my home value?
Generally, movable furniture does not improve the resale value of your home in the same way that permanent fixtures or renovations do. Focus on furniture for its comfort and utility, not as a tool for financial gain.
This content is provided for educational purposes only and does not constitute financial, investment, or tax advice. Financial situations vary significantly between individuals. Before making major purchasing decisions or changing your financial strategy, it is recommended that you consult with a qualified financial advisor who understands your personal circumstances and long-term goals. There is no guarantee that any financial strategy will lead to a specific outcome.











